Speak with a licensed insurance agent

1-855-454-9051

TTY user 711 Mon-Fri : 8am-9pm EST

Medicare Advantage Plans 2027: Costs, Benefits and How to Compare

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 9, 2026

Choosing among Medicare Advantage plans for 2027 means weighing coverage, network rules, extra benefits, and cost against your own health needs and budget.

This guide walks through everything that goes into that decision — how Medicare Advantage works, what’s changing for 2027, the four main plan types, what plans typically cost, how star ratings work, and exactly when you can enroll.

If you already know what you’re looking for, you can jump straight to compare 2027 Medicare Advantage plans in your area by ZIP code. Otherwise, read on — this guide covers the full picture.

If you’re comparing insurers rather than researching the program itself, see which carriers have the best Medicare Advantage plans for 2027, compared side by side on cost, star ratings and availability.

And before you compare plans at all, make sure Medicare Advantage is the right path for you. Our side-by-side on Medigap vs Medicare Advantage walks through how the costs, doctor networks and switching rules differ, including the enrollment window that does not come back.

Not sure Medicare Advantage is the right structure for you in the first place? Start with Original Medicare vs Medicare Advantage — it covers what each one costs, how doctor access differs, and the out-of-pocket gap that decides it for most people.

✔ Licensed across all 50 states✔ Built on CMS 2027 data✔ No-cost plan comparison

View Medicare Advantage Plans for 2027

Speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08

PREMIUMS FELL. YOUR EXPOSURE ROSE.

CMS confirmed that the average Medicare Advantage premium drops from $14.37 a month to $12.00 for 2027, a fall of 16.5%. That is the number every article will lead with, and it is true.

It is also not the number that decides what you spend. Published plan data shows maximum out-of-pocket limits rose about 10% for 2027 and Part D deductibles rose about 30%. The monthly price came down because the ceiling on a bad year went up. Compare the cap and the drug deductible before you compare the premium.

Live in Illinois? Plans drop from 157 to 136 for 2027, and Blue Cross Illinois is cutting back sharply. See our guide to Medicare Advantage plans in Illinois 2027.

What Is Medicare Advantage? (Medicare Part C Explained)

Medicare Advantage, also called Medicare Part C, is an alternative way to receive your Medicare benefits. Instead of getting coverage directly through the federal government (Original Medicare), you enroll in a plan offered by a private insurance company that’s approved by and contracts with Medicare.

Every Medicare Advantage plan is required to cover everything Original Medicare Part A (hospital coverage) and Part B (medical services) cover. Some plans in 2027 may go further, bundling in additional benefits Original Medicare doesn’t include on its own — these may include:

✔

Prescription drug coverage (Part D), bundled into the plan

✔

Dental, vision, and hearing coverage

✔

Over-the-counter (OTC) allowances for health items

✔

Fitness program memberships and transportation to medical appointments

In exchange for these added benefits, most Medicare Advantage plans use a provider network — meaning your choice of doctors and hospitals may be more limited than with Original Medicare, depending on the plan type you choose.

Seen the term MAPD and not sure what it means? It stands for Medicare Advantage Prescription Drug — a plan with Part D coverage built in. Our guide to MAPD 2027 explains what is included, how it differs from a standalone drug plan, and what it costs.

What's Now Public for 2027 Plans

The plan-level detail for 2027 is now public. CMS released the 2027 Medicare Advantage landscape on September 28, 2026, and Medicare Plan Finder went live with plan-by-plan detail on October 1. The national average Medicare Advantage premium for 2027 is $12.00 a month, down from $14.37 in 2026, but averages hide a lot of movement in individual plans.

You can now see these for every plan in your county:

✔

The monthly premium and medical deductible for each 2027 plan

✔

The maximum out-of-pocket limit, which caps what you can be charged for covered medical care

✔

Provider networks, so you can check whether your own doctors and hospitals are in network for 2027

✔

Drug formularies and tier placement, so you can check your specific prescriptions rather than guessing

✔

Supplemental benefits such as dental, vision, hearing and over-the-counter allowances, with their actual dollar amounts

✔

The 2027 star rating for each plan, which CMS released on October 8, 2026

✔

Which plans are being discontinued in your area, and what your carrier is moving you into if you do nothing

With the plan data and the 2027 star ratings both out, you have everything you need to compare before enrollment opens on October 15.

Use the days before October 15, not the last two weeks of November

Most people wait until enrollment opens and then rush. The people who choose well use the time before the window starts to check three things: whether their doctors are still in network, whether their prescriptions are still covered at the same tier, and whether their current plan still exists in 2027. If any of those three has changed, you have a decision to make and extra time to make it.

What's New for Medicare Advantage Plans in 2027

The Centers for Medicare & Medicaid Services (CMS) released the 2027 plan landscape on September 28, 2026, plan-by-plan detail went live on Medicare Plan Finder on October 1, and the 2027 Star Ratings followed on October 8. Here’s what the 2027 Medicare Advantage plans data shows:

✔

Premiums — the national average Medicare Advantage premium is $12.00 a month for 2027, down from $14.37 in 2026, though individual plans in your county can still rise

✔

Plan choices — 5,532 Medicare Advantage plans are available nationally, compared with 5,553 for 2026, and plan options shrink in 29 states and jurisdictions

✔

Out-of-pocket costs — industry analysts report that average out-of-pocket maximums and Part D deductibles are rising for many plans, even where premiums fall

✔

2027 Star Ratings — the average rating dipped to 3.99 from 4.01, only 15 contracts earned 5 stars (down from 22), and about 71% of members are in plans rated 4 stars or higher (see the Star Ratings section below)

✔

Carrier and network changes — insurers exiting some counties and entering others, so whether your current plan continues depends on where you live

That list is the short version. For the full breakdown of every Medicare Advantage plan change for 2027 — what carriers are cutting, what is being added, how benefits and costs move, and which changes are already confirmed — see our dedicated guide.

One carrier change stands out as the largest. Humana is discontinuing plans covering roughly 600,000 members, with non-renewal letters dated October 2, 2026 and affected coverage ending December 31. If you hold a Humana plan, our page on which Humana plans are ending covers how to confirm whether yours is one of them and what your options are.

Plan premiums are only half the picture. Whichever 2027 plan you choose, you still pay the standard Medicare Part B premium on top of it, and that amount is set by CMS rather than by any insurer. For the projected figures, the income-related surcharges that hit higher earners, and the announcement timeline, see the 2027 Medicare Part B premium.

Not every carrier is pulling back. Kaiser Medicare Advantage plans 2027 covers the one major carrier that is not leaving any state, sells in nine states plus DC, rated 4 stars or higher on every contract again for 2027, and holds a 5-star contract in Nevada.

2027 Medicare Advantage plan details are now public on Medicare Plan Finder. You can enroll during the Medicare Annual Enrollment Period, October 15 – December 7, 2026, for coverage effective January 1, 2027.

CMS has already finalized the 2027 rules

Plans are being paid 2.48% more next year, chronic-illness benefit rules are tightening, and debit card disclosures are changing. Those apply alongside the plan-level changes carriers published on October 1.

See the full breakdown of Medicare Advantage plan changes for 2027, including what is confirmed and what is still speculation.

Compare Medicare Advantage plans for 2027; plans, benefits, rates

View available plans in your area

Or speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08

How Medicare Advantage Star Ratings Work

Each fall, CMS scores every Medicare Advantage plan on a scale of 1 to 5 stars based on quality and performance measures, including member satisfaction, customer service, chronic condition management, and preventive care outcomes. These ratings matter for a few reasons:

✔

Quality signal — a higher star rating generally reflects stronger member experience and care coordination

✔

5-Star Special Enrollment Period — if a 5-star plan is available in your area, you can switch into it once during a special enrollment window outside the standard Annual Enrollment Period

✔

Bonus payments — plans with 4+ stars receive bonus payments from CMS, which many carriers reinvest into richer supplemental benefits

2027 STAR RATINGS — RELEASED OCTOBER 8, 2026

The average rating for plans with drug coverage dipped to 3.99 from 4.01. Only 15 contracts earned 5 stars, down from 22, while about 71% of members are in plans rated 4 stars or higher. Among carriers, Humana jumped to about 95% of members in 4-star-plus plans. See the full 2027 Medicare Advantage star ratings breakdown and every 5-star Medicare Advantage plan.

What Carriers Are Cutting for 2027: Benefit “Shrinkflation”

CMS is paying Medicare Advantage plans 2.48% more in 2027, yet most carriers are not making plans richer. The money is going to cover medical costs that rose faster than that, plus the new $2,400 cap on what members pay for drugs, which shifts drug spending from the member onto the plan. Something has to give, and it is usually the extras rather than the premium. The industry term for it is benefit shrinkflation: the plan still lists dental, vision, hearing, over-the-counter and transportation, but each one is worth less than it was.

Early analysis of 2027 filings bears this out. Industry analysts at Leerink found average out-of-pocket maximums up about 10% and Part D deductibles up about 30%, even as the national average Medicare Advantage premium fell to $12.00 a month from $14.37.

This is why a plan can look identical year over year and still cost you more. Here is where the trimming usually shows up, and what to check on your own plan now that 2027 details are public.

Benefit How it gets trimmed What to check
Over-the-counter allowance A smaller quarterly amount, a narrower product list, or the allowance dropped entirely The dollar amount per quarter, and whether unused money rolls over
Dental A lower yearly allowance, preventive-only coverage, or a tighter dental network The comprehensive allowance, and whether your own dentist is covered
Flex cards A smaller balance, or restrictions on what the card can be spent on The balance and the list of eligible categories, not the advertised headline
Transportation and meals Fewer one-way rides or delivered meals per year The exact number of rides or meals included
Vision and hearing A lower eyewear or hearing aid allowance, or a limited supplier list The allowance and which suppliers accept it
Cost sharing A higher maximum out-of-pocket, or higher copays for specialists and hospital stays The in-network maximum out-of-pocket, the number that caps your worst year

A $0 premium is not the same as no change. Carriers protect the $0 premium because it is what sells the plan. The reductions land in the benefits underneath it, which is exactly why the Annual Notice of Change matters more than the advertisement.

CMS also finalized rules for 2027 that tighten which chronic-illness extra benefits plans may offer and change how plan debit cards must be disclosed. Both push in the same direction: fewer loosely defined extras, more disclosure about what the card actually buys.

What to do about it. Read the Annual Notice of Change your plan mailed by September 30, then compare the 2027 allowance amounts line by line against what you actually used this year. An extra you never use being cut costs you nothing. The one you rely on being cut is a reason to switch plans, and the Annual Enrollment Period, October 15 to December 7, 2026, is when you can.

Medicare Advantage Plan Types for 2027: A Deep Dive

There are four main types of Medicare Advantage plans, each offered by different insurance companies with different network rules, costs, and flexibility. Compare Aetna Medicare Advantage plans 2027 and Humana Medicare Advantage plans 2027 to see how the two largest carriers differ. Here’s how each plan type actually works, plus the trade-offs of each.
Four types of Advantage plans

Health Maintenance Organization (HMO) Plans

HMO plans generally require you to choose a primary care physician and get care from doctors and hospitals within the plan’s network, except for emergency or urgent care. Many HMOs bundle in Part D prescription drug coverage — if your HMO includes it, you can’t also enroll in a stand-alone Part D plan.

⭐ Best For: people who want lower costs and don’t mind coordinating care through a primary doctor and staying in-network.

Preferred Provider Organization (PPO) Plans

PPO plans also use a network, but you can see out-of-network providers at a higher cost. Most PPO plans include prescription drug coverage — check your specific medications’ cost tier and confirm your doctors accept the plan. No primary care referral is required, and costs are typically lower when you stay in-network.

⭐ Best For: people who want more flexibility to see specialists without referrals or who split time between two locations (like snowbirds).

Private Fee-for-Service (PFFS) Plans

With a PFFS plan, the plan — not a network — sets how much it pays providers, and the provider must agree to those terms for each visit. You can see any Medicare-approved provider who accepts the plan’s terms, but visiting a non-participating provider can mean significantly higher costs. Some PFFS plans include Part D coverage; if not, you can enroll in a stand-alone Part D plan.

⭐ Best For: people in rural areas with fewer network-based plan options available.

View Medicare Advantage Plans for 2027

Speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08

In Michigan, average premiums are rising for 2027 even as they fall nationally. See our guide to Medicare Advantage plans in Michigan 2027.

Special Needs Plans (SNPs)

SNPs restrict enrollment to people who meet specific eligibility criteria — a qualifying chronic condition, dual eligibility for Medicare and Medicaid, or residence in an institution. Most operate like an HMO with a defined network and a care coordinator, and every SNP is required to include Part D prescription coverage. Benefits and provider networks are built around the condition or population the plan serves.

⭐ Best For: people managing a qualifying chronic condition (like diabetes or heart failure) or who are dual-eligible for Medicare and Medicaid.

2027 Medicare Advantage Plans Comparison Chart

The four plan types side by side on the rules that actually change what you pay and who you can see.

Plan type Network rules Referral needed Out-of-network care Part D included
HMO Must use the plan’s network; primary care physician generally required Usually yes, for specialists Emergency and urgent care only Usually — if it is, you cannot add a separate Part D plan
PPO Network preferred, but you may go outside it No Covered, at a higher cost share Usually — verify your drugs and their tiers
PFFS No network in most cases; the plan sets payment terms No Any Medicare provider who accepts the plan’s terms, checked visit by visit Sometimes — if not, you can add a stand-alone Part D plan
SNP Network-based, usually HMO-style, with a care coordinator Usually yes Emergency and urgent care only Always — required for every SNP

These are the general rules for each type. Individual plans vary, so confirm

View available plans in your area

Or speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08

List of Medicare Advantage Plans for 2027

There are 5,532 Medicare Advantage plans available nationally for 2027, sold by private insurers approved by Medicare. Which of them you can buy depends on your county, so the most useful list is the one for your ZIP code. Here are the major carriers offering 2027 plans, with our guide to each:

✔

UnitedHealthcare Medicare Advantage plans — the largest carrier by enrollment, with HMO, PPO and Special Needs Plans in most states

✔

Humana Medicare Advantage plans — the second largest carrier, discontinuing plans covering roughly 600,000 members for 2027 while adding coverage in some counties

✔

Aetna Medicare Advantage plans — sold in 43 states plus DC, with strong 2026 star ratings across a wide footprint

✔

Kaiser Permanente Medicare Advantage plans — the highest rated carrier, sold in nine states plus the District of Columbia

✔

Blue Cross Blue Shield and Anthem plans — sold by regional companies, so plan options vary widely from state to state

✔

Devoted Health — the fastest-expanding carrier for 2027, adding 336 counties

Every carrier’s plans fall into a few types, and the type decides your network rules:

✔

HMO plans — the most common type, using a set network, usually with lower costs

✔

PPO plans — more freedom to see providers outside the network, at a higher cost

✔

Special Needs Plans (SNPs) — for people with certain chronic conditions or dual Medicare and Medicaid eligibility

✔

PFFS plans — less common, with no network in most cases

For a ranked view, see our best Medicare Advantage plans 2027 and the 2027 Medicare Advantage plans by carrier comparison. To see the exact list of plans in your county, enter your ZIP code at the top of this page.

What to Compare in a 2027 Medicare Advantage Plan

Medicare Advantage Plans 2027 Comparison

Comparing 2027 Medicare Advantage plans side by side is the only way to see which one actually fits your doctors, your prescriptions, and your budget – because two plans in the very same ZIP code can differ by thousands of dollars a year.

Here’s exactly what to compare, and how to line the plans up so the right one is easy to spot.

These are the factors that decide your real cost and quality of care. Weigh every plan against all of them – not just the premium:

✔

Monthly premium – many Medicare Advantage plans are $0, but $0 doesn’t always mean the lowest total cost.

✔

Maximum out-of-pocket (MOOP) – the yearly cap that protects you if you get sick. Lower is better.

✔

Provider network – confirm your doctors and hospitals are in-network. HMO vs PPO makes a big difference here.

✔

Prescription drug coverage (Part D) – check each plan’s formulary for your specific medications and their tiers.

✔

Extra benefits – dental, vision, hearing, OTC allowance, fitness, and transportation vary widely from plan to plan.

✔

CMS Star Rating – Medicare’s 1–5 quality score. A 4+ rating signals a well-run plan. See our full guide to the Medicare Advantage star ratings for what the score measures and where each carrier stands.

✔

Plan type & rules – HMO, PPO, PFFS, or a Special Needs Plan (SNP), and whether referrals or prior authorization are required (see the chart below).

How to Compare Medicare Advantage Plans 2027 Side by Side

1

Enter your ZIP code on this page to show 2027 plans available in your county.

2

Filter by what matters most to you – $0 premium, a specific carrier, or plan type.

3

Line the plans up on the factors above: premium, MOOP, network, drugs, extras, and star rating.

4

Confirm your doctors are in-network and your prescriptions are on the formulary.

5

Compare the total estimated yearly cost – not just the monthly premium – then check the star rating.

Medicare’s own comparison tool is where a lot of people start, and it is worth knowing both what it does well and where it leaves you on your own. Our guide to the Medicare Plan Finder tool covers the settings that quietly change your results, the gaps it does not cover, and the checks you still have to make yourself before enrolling.

Availability and cost vary enormously by state and county, which is why a national comparison only takes you so far. Florida is the clearest example, with one of the largest and most competitive markets in the country — our guide to Medicare Advantage plans in Florida covers which carriers compete there and how coverage differs between the metros and the rural counties.

California is the other end of the same lesson. It has more Medicare Advantage members than any state in the country, about 3.68 million, yet it sits almost exactly at the national median on how often people choose Advantage over Original Medicare. Our guide to Medicare Advantage plans in California covers the carriers competing there, the two separate Blue plans that confuse people every year, and why plan counts swing from more than a hundred in Los Angeles County down to zero in two counties.

Some states are shaped by history rather than size. Medicare Advantage plans in Minnesota show how far a single state can diverge — Minnesota runs ahead of the national enrollment average, has its own Medicare Supplement rules under a federal waiver, and is the one state where Medicare Cost plans were a dominant product before they were largely eliminated in 2018.

Ohio is the case for the opposite problem. The average Ohio beneficiary can choose from around 62 Medicare Advantage plans, one of the highest figures in the country, which turns the exercise from finding a plan into filtering out 61 of them. Our guide to Medicare Advantage plans in Ohio covers the regional carriers tied to each metro health system, and a gap in Ohio law that leaves 270,000 beneficiaries without any Medicare Supplement option at all.

Pennsylvania is the clearest example of a state that behaves like three separate markets. Roughly 1.6 million Pennsylvanians are in an Advantage plan, close to 58 percent, but which carriers compete for you depends entirely on where you live — western counties are dominated by health systems that own both the hospitals and the insurance plan, the Philadelphia region is a separate competitive market, and the central and northern tiers have noticeably thinner choices. Our guide to Medicare Advantage plans in Pennsylvania covers all three and why hospital affiliation matters more than premium there.

In the mid-Atlantic, upstate New York and Pennsylvania, regional carriers compete head to head with the national names. Compare CareFirst Medicare Advantage plans 2027 across Maryland and Washington, D.C., Excellus Medicare Advantage plans 2027 across Rochester, Central New York and the North Country, CDPHP Medicare Advantage plans 2027 in the Capital Region, UPMC Medicare Advantage plans 2027 in western Pennsylvania, and Geisinger Medicare Advantage plans 2027 in central and north-eastern Pennsylvania.

Carrier names change too. Cigna no longer sells Medicare plans under its own name — if you held a Cigna plan or are seeing the HealthSpring name for the first time, here is what happened to Cigna Medicare and who runs those plans now.

In Minnesota and western Wisconsin, the local plan to weigh against the national carriers is HealthPartners, which sells PPO plans only and still offers old-style Medicare Cost plans in seven Wisconsin counties. See HealthPartners Medicare Advantage plans 2027.

Use the quick reference below to see how the 2027 plan types stack up, then compare the plans in your area by ZIP code or call a licensed insurance agent at 1-855-454-9051 (TTY 711).
2027 Medicare Advantage Plan Comparison at a Glance

Plan Type Network Rule See Any Doctor? Rx Included? Referral Needed?
HMO In-network only (except emergencies) No Usually yes Often, for specialists
PPO In-network preferred, out-of-network allowed at higher cost Yes, at higher cost out-of-network Usually yes No
PFFS Plan sets payment terms; provider must accept Any Medicare-approved provider who accepts plan terms Sometimes No
SNP Tailored network for qualifying condition/status No Usually yes Often

Medicare Advantage vs. Original Medicare vs. Medicare Supplement

One of the most common points of confusion is how Medicare Advantage differs from Original Medicare and from Medicare Supplement (Medigap) insurance. Here’s the short version:

✔

Original Medicare (Parts A & B) is run directly by the federal government. You can see almost any doctor who accepts Medicare nationwide, but it doesn’t cap your out-of-pocket costs and doesn’t include prescription drug, dental, vision, or hearing coverage on its own.

✔

Medicare Advantage (Part C) replaces Original Medicare with a private plan that typically uses a network, caps your annual out-of-pocket spending, and often bundles in drug coverage and extra benefits.

✔

Medicare Supplement (Medigap) works alongside Original Medicare — not instead of it — to help cover the out-of-pocket costs Original Medicare leaves behind, like copays and coinsurance. Medigap generally doesn’t use networks and doesn’t include extra benefits or drug coverage; you’d need a separate Part D plan.

Medicare advantage vs original Medicare

What Do 2027 Medicare Advantage Plans Cost?

✔

Monthly premium: many 2027 Medicare Advantage plans offer $0 premiums, but availability depends on your area and carrier — you’ll still pay your Medicare Part B premium

✔

Deductibles & copays: vary by plan; always confirm against the plan’s Summary of Benefits before enrolling

✔

Out-of-pocket maximum: all Medicare Advantage plans are required to cap your annual out-of-pocket costs, unlike Original Medicare alone

✔

Extra benefits: dental, vision, hearing, OTC allowances, and fitness benefits vary widely by plan and ZIP code

A simple way to think about it: a low or $0 premium plan isn’t automatically the cheapest option overall. Look at the total picture — premium, deductible, copays, and your specific prescriptions — before comparing plans on price alone.

Costs also swing hard by state and county. Georgia is a good example: more than half its Medicare population is already on Advantage, yet plan counts run from around 20 in some counties to more than 50 in others. Our guide to Medicare Advantage plans in Georgia breaks down the carriers, the star ratings and the metro versus rural gap.

What CMS Confirmed For 2027

Measure 2026 2027
Average Medicare Advantage premium $14.37 $12.00
Average standalone drug plan premium $35.09 $36.00
Drug coverage inside an MA plan $11.32 $7.00
Plans available nationally 5,553 5,532
Projected enrollment About 35 million 34 million
Out-of-pocket maximums — Up about 10%
Part D deductibles — Up about 30%

One caveat on that premium figure. The $12.00 average includes special needs plans, which pull it downward. Weighted across the plans most people actually shop, analysts put the industry average closer to flat year over year. Treat the 16.5% fall as a headline, not as what will happen to your bill.

View plans & benefits for your zip code

Speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08

Medicare Advantage Enrollment Periods for 2027

Ready to act? Medicare open enrollment 2027 runs October 15 to December 7, 2026 — see the full calendar, what you are allowed to change, and the five things to check before the window opens.

New to Medicare?

The best time to enroll in a 2027 Medicare Advantage plan is during your Initial Enrollment Period (IEP) — the 3 months before your 65th birthday month, your birthday month, and the 3 months after.

December 7 is not the last window of the year. If you are already in a Medicare Advantage plan, the Medicare Advantage Open Enrollment Period runs January 1 through March 31 and gives you one more chance — switch plans or return to Original Medicare. That page covers every enrollment window and exactly what each one allows.

Coverage begins the first of the month after you enroll.

Already Enrolled in Medicare?

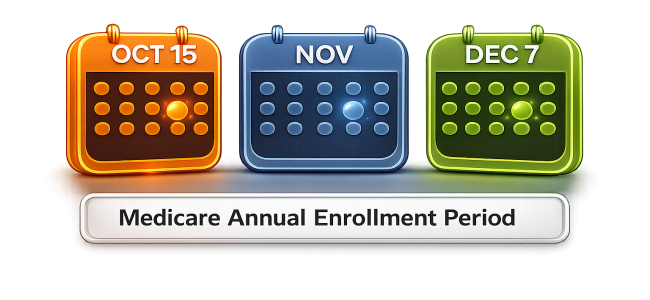
You can switch to or enroll in a Medicare Advantage plan during the Annual Enrollment Period (AEP), which runs October 15 – December 7, 2026, for coverage effective January 1, 2027.

Already in a Medicare Advantage Plan?

Current MA enrollees also get the Medicare Advantage Open Enrollment Period, January 1 – March 31, to switch to a different MA plan or return to Original Medicare — once per year.

Medicare advantage plans enrollment period 2027

Who Should Consider a Medicare Advantage Plan?

Medicare Advantage tends to be a good fit if you:

✔

Want dental, vision, hearing, or OTC benefits bundled into one plan (*not available in all plans)

✔

Are comfortable using a network of doctors and hospitals

✔

Want a cap on your annual out-of-pocket medical costs

✔

Prefer a single monthly premium instead of separate Medigap and Part D premiums

Original Medicare plus a Medicare Supplement may be a better fit if you:

✔

Travel frequently or split time between multiple states

✔

Want the widest possible choice of doctors and specialists nationwide with minimal network restrictions

✔

Prefer more predictable, capped out-of-pocket costs per service over bundled extra benefits

Quality is the one dimension Medicare scores for you. Only 15 contracts nationwide hold five stars for 2027, and our guide to top rated Medicare Advantage plans lists every one of them, explains what the ratings measure, and covers the enrollment rule that applies only to 5-star plans.

One genuinely new thing for 2027: a retailer is on a Medicare Advantage plan for the first time. Costco is offering Medicare Advantage plans in 17 California counties and 2 Nevada counties, co-branded with SCAN Health Plan, with an allowance you spend on over-the-counter products and health food at Costco stores.

Medicare Advantage Carriers Compared by 2027 Star Rating

CMS scores every Medicare Advantage contract from 1 to 5 stars on clinical quality, member experience and customer service. CMS released the 2027 Star Ratings on October 8, 2026. The table shows each carrier’s share of members in 4-star-plus plans for 2027 next to 2026. Where a carrier has not yet published its figure, we show the direction reported so far and will update the table as numbers come in.

Carrier Members in 4+ star plans, 2027 2026 What it means for you
Humana About 95% 20% The biggest turnaround of 2027, with 18 contracts at 4 stars or higher, including six at 4.5
Aetna (CVS Health) More than 69% 81% Slipped for 2027 but still has most members in well-rated plans across 43 states plus DC
UnitedHealthcare About 67% (analyst estimate) 78% The largest carrier by enrollment; down for 2027, but holds three of the 15 five-star contracts
Kaiser Permanente Every contract 4 stars or higher 100% The 2026 quality leader, and its Nevada contract earned 5 stars for 2027; sells in nine states plus DC
Elevance Health (Anthem) Lower (not yet published) 55% Some contracts slipped below 4 stars for 2027; its Anthem HP contract kept 5 stars
HealthSpring Lower (not yet published) 47% The former Cigna Medicare plans, now run by Health Care Service Corporation, which lost ground for 2027
Wellcare (Centene) Lower (not yet published) 20% Still the lowest of the national carriers, with some contracts slipping below 4 stars for 2027

Only 15 Medicare Advantage contracts with drug coverage earned 5 stars for 2027, down from 22 for 2026. The national enrollment-weighted average dipped to 3.99 from 4.01, and about 71 percent of members are in plans rated 4 stars or higher. Devoted Health and Alignment Health, which held 5-star contracts for 2026, are not on the 2027 list. See every one of the 15 in our guide to top rated Medicare Advantage plans.

A carrier average is not your plan rating

Star ratings are assigned to individual contracts, not to companies, so the same carrier can hold 4.5 stars in one state and 3.5 in the next. Use the figures above to see which carriers are trending well nationally, then check the 2027 rating on the specific plans offered in your own county, which now shows next to every plan in Medicare Plan Finder.

SNPs are the fastest-growing part of Medicare Advantage, accounting for roughly 85 percent of all enrollment growth in 2026. Our guide to Medicare Advantage Special Needs Plans covers who qualifies for each of the three types, the 22 chronic conditions CMS now recognizes, and the new aligned enrollment rules for 2027.

PPOs are the plan type most often chosen for network freedom, and the one most often misunderstood. Our guide to Medicare Advantage PPO plans covers what out-of-network care actually costs, the two out-of-pocket maximums every PPO carries, and why a PPO still requires prior authorization.

Which Carriers Cut Plans For 2027

Every major carrier reduced its individual plan count for 2027. These figures come from analysts reading the published plan data rather than from carrier announcements, so treat them as close estimates rather than official counts — but the direction and scale are clear.

Carrier Plans cut Counties
Centene / Wellcare About 3,000 Exiting 344
Humana About 2,400 Adding 39
UnitedHealthcare About 690 Exiting 63
Elevance About 150 Exiting 56
CVS / Aetna Not disclosed Exiting 123, plus Maryland and New Hampshire
Devoted Health None reported Adding 336
Alignment Health None reported Adding 9

SOMEBODY IS GROWING

While the largest carriers pulled back, Devoted Health added 336 counties for 2027 — the single biggest expansion of any carrier — and Alignment added nine. If your plan is going away, there may be a new option in your county that was not there last year.

Comparing carriers? See what is changing for 2027 in our guide to UnitedHealthcare Medicare Advantage plans 2027, including plan cuts, county exits and average cost increases.

Smaller insurers are growing too. Zing Health expands from 52 to 63 counties for 2027 across six Midwest and Southern states; see Zing Medicare Advantage plans 2027.

View Plans Now

Speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08

Medicare Advantage Plans 2027 — Frequently Asked Questions

➤ What’s new for Medicare Advantage plans in 2027?

Each fall, CMS finalizes updated premiums, star ratings, and supplemental benefits for the coming plan year. 2027 plan details are released to the public during the Medicare Annual Enrollment Period, October 15–December 7, 2026, with coverage starting January 1, 2027.

➤ How much do Medicare Advantage plans cost in 2027?

Many Medicare Advantage plans offer $0 monthly premiums, though availability depends on your ZIP code and the carriers in your area. You’ll still need to pay your Medicare Part B premium regardless of which plan you choose.

➤ When can I enroll in a 2027 Medicare Advantage plan?

The Medicare Annual Enrollment Period (AEP) runs October 15 through December 7, 2026, for coverage effective January 1, 2027. If you’re new to Medicare, you can also enroll during your Initial Enrollment Period.

➤ What’s the difference between Medicare Advantage and Medicare Supplement plans?

Medicare Advantage (Part C) plans bundle Part A, Part B, and often Part D and extra benefits into one plan, typically using a provider network. Medicare Supplement plans work alongside Original Medicare and generally don’t use networks, but don’t include extra benefits or drug coverage.

➤ Can I switch Medicare Advantage plans every year?

Yes. You can switch during AEP (October 15–December 7). There’s also a Medicare Advantage Open Enrollment Period from January 1 to March 31 for current MA enrollees to make one additional switch.

➤ Do all Medicare Advantage plans include prescription drug coverage?

Most do, but not all. If a plan doesn’t include Part D drug coverage, you can typically enroll in a stand-alone Part D plan separately — but if your Medicare Advantage plan already includes drug coverage, you generally can’t also enroll in a separate Part D plan.

➤ What happens if I move to a different state or county?

Moving outside your plan’s service area typically triggers a Special Enrollment Period, allowing you to choose a new Medicare Advantage plan or switch back to Original Medicare outside of the standard enrollment windows.

➤ Are Medicare Advantage star ratings the same every year?

No. CMS recalculates star ratings annually based on the most recent performance and satisfaction data, so a plan’s rating for 2027 may differ from its 2026 rating — it’s worth checking each year even if you’re happy with your current plan.

➤ What should you compare when choosing a 2027 Medicare Advantage plan?

Focus on the factors that drive your real cost and care: the monthly premium and maximum out-of-pocket, whether your doctors are in-network, whether your medications are covered, the extra benefits included (dental, vision, hearing, and more), and the plan’s star rating.

➤ How do I compare Medicare Advantage plans for 2027?

Enter your ZIP code below on this page to see plans available in your county, then compare them by premium, maximum out-of-pocket, provider network, drug coverage, extra benefits, and CMS star rating.

Before you choose, confirm your doctors are in-network and your prescriptions are on the plan’s formulary.

➤ Is there a tool to compare 2027 Medicare Advantage plans side by side?

Yes – right on this website! Just enter your ZIP code above to line up the 2027 Medicare Advantage plans available in your area side by side, or call one of our licensed insurance agents at 1-855-454-9051 (TTY 711) to walk through the comparison with you.

➤ What is the best Medicare Advantage plan for 2027?

There is no single best plan, because plans are sold county by county and the right one depends on your doctors, your prescriptions and your ZIP code. On the 2027 star ratings, Humana now puts about 95% of its members in plans rated 4 stars or higher, the highest share of the large national carriers, with Aetna at more than 69%. Kaiser Permanente rated 4 stars or higher on every plan for 2026 and holds a 5-star contract in Nevada for 2027, but it only sells in eight states and the District of Columbia. See our ranked comparison of the best Medicare Advantage plans 2027.

➤ How much will Medicare Advantage plans go up in 2027?

On premiums, the average is going down: the national average Medicare Advantage premium for 2027 is $12.00 a month, down from $14.37 in 2026. Other costs are moving the other way, with industry analysts reporting average out-of-pocket maximums up about 10% and Part D deductibles up about 30%. Already set: the Part B premium is projected at $209.50 a month for 2027, up from $202.90; the Part D deductible rises to $700 from $615; and the yearly cap on prescription costs rises to $2,400 from $2,100. CMS is also paying Medicare Advantage plans 2.48% more in 2027, which is why many carriers are holding $0 premiums while trimming extra benefits instead.

➤ Are seniors going to lose their Medicare Advantage plans?

Some will. Carriers drop plans and exit counties every year, and for 2027 Humana alone is discontinuing plans covering roughly 600,000 members, with non-renewal letters dated October 2, 2026 and coverage ending December 31. Medicare Advantage itself is not going away, and anyone whose plan ends gets a special enrollment period to choose new coverage. See are Medicare Advantage plans going away in 2027 for what to do if you get a letter.

Have Questions?

Speak with a licensed insurance agent

1-855-454-9051

TTY users 711

Mon-Fri: 8am-9pm ET

Find & Compare Plans Online

Speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08

ZRN Health & Financial Services, LLC, a Texas limited liability company