Speak with a licensed insurance agent

1-855-454-9051

TTY user 711 Mon-Fri : 8am-9pm EST

MAPD 2027: What MAPD Means, Coverage & Costs

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated September 28, 2026

If you have seen “MAPD” on a plan document or heard an agent use it and had no idea what it meant, you are in the right place. It is not a different kind of insurance and it is not a government programme. It is shorthand, and once you know what it stands for the rest of Medicare shopping gets noticeably simpler.

What MAPD stands for - Medicare Advantage plus Part D prescription drug coverage in one plan

What Does MAPD Stand For?

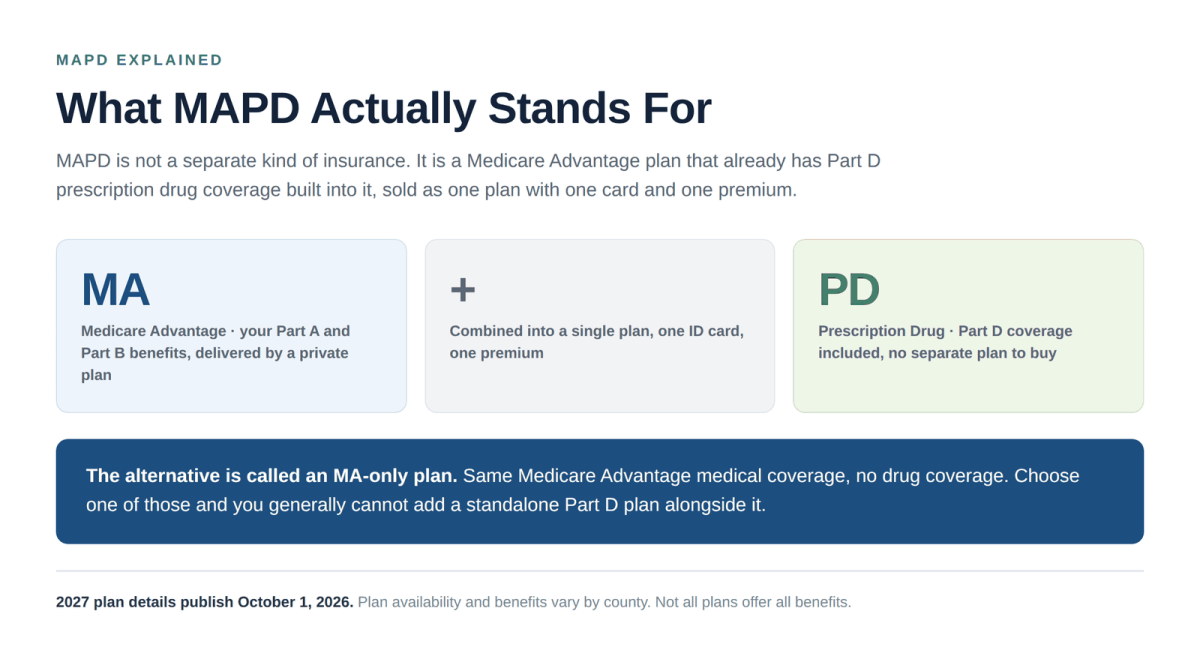
MAPD stands for Medicare Advantage Prescription Drug. An MAPD plan is a Medicare Advantage plan that already has Part D prescription drug coverage built into it. One plan, one ID card, one premium, one company to call.

The short version. MA is Medicare Advantage, your Part A and Part B benefits delivered through a private plan. PD is prescription drugs, the Part D coverage. Put them together in one policy and you have an MAPD.

The alternative is called an MA-only plan: the same Medicare Advantage medical coverage with no drug coverage attached. Those exist mainly for people who get drug coverage somewhere else, such as through the VA or a former employer. Most Medicare Advantage plans sold to individuals are MAPD plans, which is why the two terms get used almost interchangeably even though they are not the same thing.

One rule catches people out: if you enrol in an MA-only plan, you generally cannot buy a standalone Part D plan to sit alongside it. Doing so will usually disenroll you from the Advantage plan. If you want drug coverage and a Medicare Advantage plan, you want an MAPD.
What An MAPD Plan Includes

Every MAPD plan has to cover everything Original Medicare covers, plus prescription drugs. Beyond that floor, plans compete on extras, and what those extras are worth varies enormously county to county.

Coverage In an MAPD plan
Hospital care (Part A) Always included
Doctor and outpatient care (Part B) Always included
Prescription drugs (Part D) Always included — this is the “PD”
Annual out-of-pocket maximum Always included, amount set by the plan
Dental, vision and hearing Commonly offered, limits vary widely
Fitness membership Commonly offered
Over-the-counter allowance Offered on many plans
Part B premium giveback Offered on some plans only

2027 benefits are not confirmed yet. Plans, premiums, drug lists and extras for 2027 become viewable on October 1, 2026 and may change from what is offered today. Not all plans offer all benefits, and availability varies by county.

The out-of-pocket maximum is the item most people overlook and the one that matters most in a bad year. Original Medicare has no cap at all. Every MAPD plan has one, and the number ranges from roughly $3,500 to $9,000 depending on the plan.

MAPD versus PDP with Original Medicare comparison of coverage, networks and costs

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08

MAPD vs PDP: Which Path To Take

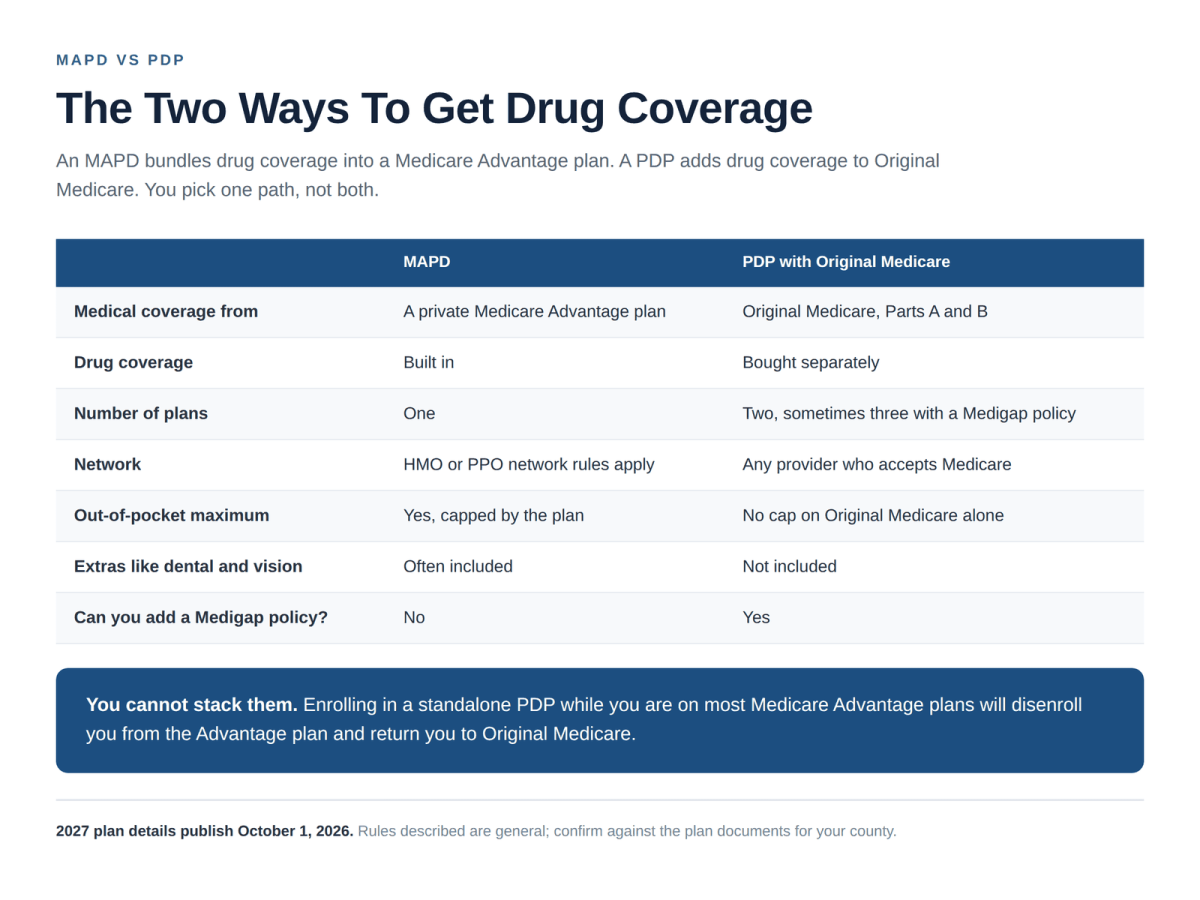
There are two ways to get prescription drug coverage on Medicare, and you choose one path rather than combining them.

MAPD PDP with Original Medicare
Medical coverage from A private Medicare Advantage plan Original Medicare, Parts A and B
Drug coverage Built in Bought separately
Number of policies One Two, or three with a Medigap policy
Choice of provider HMO or PPO network rules apply Any provider who accepts Medicare
Out-of-pocket maximum Yes, capped by the plan No cap on Original Medicare alone
Dental, vision, hearing Often included Not included
Can you add Medigap? No Yes

YOU CANNOT STACK THEM

Enrolling in a standalone PDP while you are on most Medicare Advantage plans will disenroll you from the Advantage plan and drop you back to Original Medicare. It is one of the most common and most expensive mistakes made during open enrollment. Pick a path deliberately rather than by accident.

The rough rule: an MAPD tends to win on simplicity, on extras and on having a hard cap in a bad year. Original Medicare with a PDP tends to win on freedom of provider and on travel. Neither is better in the abstract — it depends on your doctors, your drugs and your county.

How Much Does An MAPD Plan Cost?

There are four numbers, and the monthly premium is the least important of them.

WHAT YOU ACTUALLY PAY

The four costs of an MAPD plan

1

Your Part B premium. You keep paying this whatever plan you choose. Some MAPD plans give part of it back.

2

The plan premium. Often $0. A $0 premium tells you nothing about whether the plan is cheap overall.

3

Copays and coinsurance. What you pay per visit, per test, per hospital day and per prescription. This is where two $0 plans stop resembling each other.

4

The out-of-pocket maximum. Your worst-case year. Compare this before you compare premiums.

Run your own prescriptions through the Medicare Plan Finder tool with the dose and your actual pharmacy. Two MAPD plans with identical premiums routinely differ by hundreds of dollars a year on drugs alone.

MAPD Plans By Carrier

Almost every major carrier sells MAPD plans, and “Aetna MAPD” or “Humana MAPD” simply means that company’s Medicare Advantage plans with drug coverage included. Where they differ is network size, star ratings, extras and which counties they serve.

Carrier Known for
Aetna MAPD plans Strongest quality scores of the nationals, around 81% of members in 4-star-plus plans
UnitedHealthcare MAPD plans Largest national footprint, more than 77% of members in 4-star-plus plans
Humana MAPD plans Wide PPO availability and a large giveback lineup
Elevance MAPD plans Improving ratings, sold under Anthem and Wellpoint branding in many states
Blue Cross MAPD plans Regional plans with deep local networks, quality varies by state
Wellcare MAPD plans The most affordable of the majors, roughly 47% of plans at $0 premium, and the fastest-improving star ratings

If you want the field ranked rather than listed, our comparison of the best Medicare Advantage plans 2027 scores each carrier on ratings, stability and availability, and the 2027 Medicare Advantage star ratings guide explains what those scores actually measure.

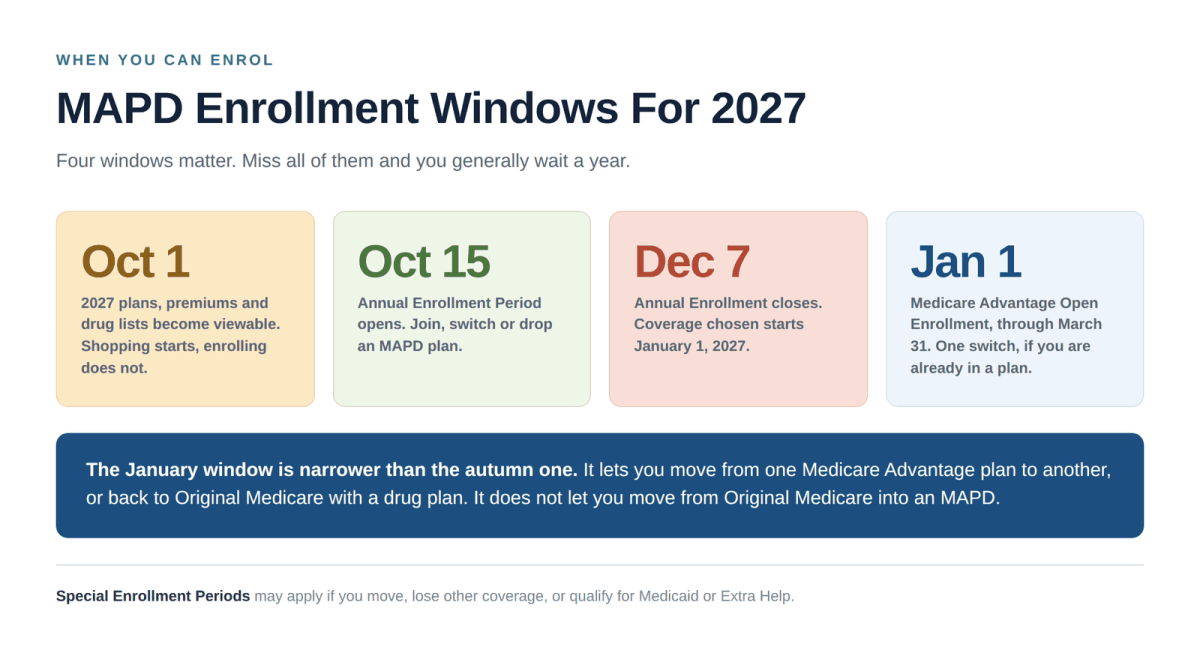
MAPD enrollment periods for 2027 including October 1, October 15, December 7 and the January window

When You Can Enrol In An MAPD Plan

Four dates matter for 2027 coverage.

Date What happens
October 1, 2026 2027 plans, premiums and drug lists become viewable. You can shop but not yet enrol.
October 15, 2026 Annual Enrollment Period opens. Join, switch or drop an MAPD plan.
December 7, 2026 Annual Enrollment closes. Your choice takes effect January 1, 2027.
January 1 to March 31, 2027 Medicare Advantage Open Enrollment. One switch, only if you are already in a Medicare Advantage plan.

WHAT THE JANUARY WINDOW DOES AND DOES NOT DO

It lets you move from one Medicare Advantage plan to another, or drop back to Original Medicare and pick up a standalone drug plan. It does not let you move from Original Medicare into an MAPD. For that you wait for the autumn. Full detail is in our guide to the Medicare Advantage open enrollment period.

Special Enrollment Periods can open outside those windows if you move out of your plan’s service area, lose employer coverage, or become eligible for Medicaid or Extra Help.

MAPD FAQs

➤  What does MAPD stand for?

MAPD stands for Medicare Advantage Prescription Drug. It is a Medicare Advantage plan with Part D prescription drug coverage built in, sold as a single plan with one ID card and one premium rather than two separate policies.

➤  What is the difference between Medicare Advantage and MAPD?

An MAPD is a type of Medicare Advantage plan. All MAPD plans are Medicare Advantage plans, but not all Medicare Advantage plans are MAPD plans. The ones that are not are called MA-only plans: identical medical coverage, no prescription drug coverage attached. Most Medicare Advantage plans sold to individuals are MAPD plans.

➤  What is the difference between an MAPD and a PDP?

An MAPD bundles medical and drug coverage into one Medicare Advantage plan. A PDP is a standalone prescription drug plan that you add to Original Medicare. They are two different paths, not two products you combine — enrolling in a standalone PDP while on most Medicare Advantage plans will disenroll you from the Advantage plan.

➤  What does an MAPD plan cover?

Everything Original Medicare covers, meaning hospital care under Part A and doctor and outpatient care under Part B, plus Part D prescription drugs and an annual cap on your out-of-pocket costs. Most plans also offer dental, vision, hearing, fitness and an over-the-counter allowance, though limits vary widely and not all plans offer all benefits.

➤  How much does an MAPD plan cost per month?

Many MAPD plans carry a $0 monthly plan premium, and some return part of your Part B premium. You always keep paying your Part B premium regardless of plan. The premium is the least useful number for comparing plans — copays, coinsurance, the drug tier your prescriptions fall into and the out-of-pocket maximum decide what you actually spend.

➤  When can I enrol in an MAPD plan?

For 2027 coverage, the Annual Enrollment Period runs October 15 to December 7, 2026, with coverage starting January 1, 2027. Plans become viewable October 1, 2026. If you are already in a Medicare Advantage plan, the Medicare Advantage Open Enrollment Period from January 1 to March 31, 2027 lets you make one further switch.

➤  Can I have an MAPD plan and a Medigap policy?

No. Medigap policies are designed to work alongside Original Medicare, not Medicare Advantage. If you enrol in an MAPD plan, a Medigap policy cannot pay toward your costs, and it is illegal for anyone to sell you one knowing you are on a Medicare Advantage plan.

New to Medicare?

If you are new to Medicare, then you can enroll in a 2027 Medicare Advantage plan up to three months prior to your Medicare Part B effective date.

Call one of our licensed insurance agents to see what the best time frame is for you to enroll, based on your current situation. You can contact them at 1-855-409-6195 (TTY 711), Mon–Fri 8am–9pm EST.

Have Questions?

Speak with a licensed insurance agent

1-855-454-9051

TTY users 711

Mon-Fri: 8am-9pm ET

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08