Speak with a licensed insurance agent

1-855-454-9051

TTY user 711 Mon-Fri : 8am-9pm EST

Disadvantages of Medicare Advantage Plans 2027: The Real Trade-offs and How to Avoid Them

Reviewed by Russell Noga, Licensed Medicare Insurance Broker (all 50 states) — Last updated October 19, 2026

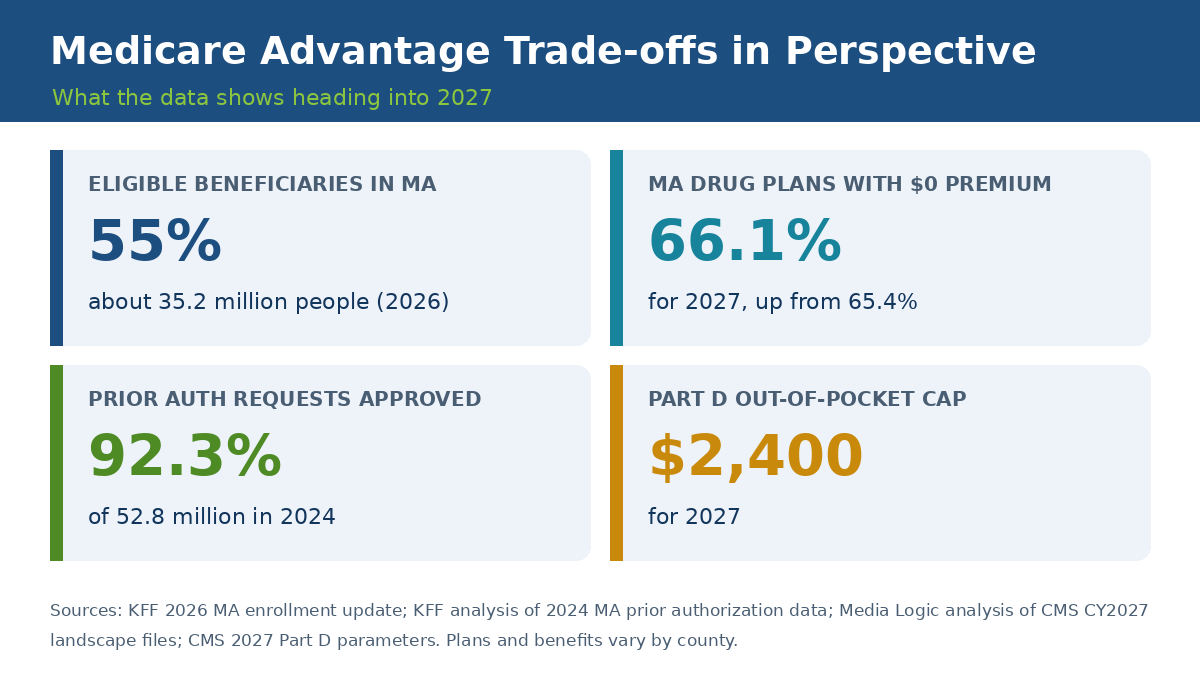
Every type of Medicare coverage has trade-offs, and Medicare Advantage is no different. The disadvantages of Medicare Advantage plans are real, but most of them are easy to manage once you know what to look for. That is a big reason 55% of eligible Medicare beneficiaries, about 35.2 million people, chose a Medicare Advantage plan in 2026.

This guide covers the main downsides people ask about, what the 2027 numbers actually show, and how to pick a plan that avoids each one. Annual Enrollment runs October 15 to December 7, 2026, so now is the time to compare.

✔ Licensed across all 50 states✔ Built on CMS 2027 data✔ No-cost plan comparison
Compare 2027 Medicare Advantage Plans in Your Area

Speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08
Disadvantages of Medicare Advantage plans in perspective: 55% of eligible beneficiaries choose Medicare Advantage, 66.1% of MA drug plans have a $0 premium for 2027, 92.3% of prior authorization requests approved, $2,400 Part D cap

Why Most People Still Choose Medicare Advantage

Before looking at the downsides, it helps to know what Medicare Advantage does well. For 2027:

✔

Low or $0 premiums. About two in three Medicare Advantage plans with drug coverage have a $0 premium, and the average Medicare Advantage premium drops to $12.00 a month, down from $14.37 in 2026.

✔

A yearly limit on out-of-pocket costs. Every Medicare Advantage plan has an out-of-pocket maximum for covered Part A and Part B services. Original Medicare has no yearly limit.

✔

Drug coverage in the same plan. Most plans include Part D, and drug costs are capped at $2,400 for 2027.

✔

Extra benefits. Many plans may include dental, vision, hearing and fitness benefits that Original Medicare does not cover, depending on the plan and area.

See how the two options compare side by side in our guide to Original Medicare vs Medicare Advantage.

7 Disadvantages of Medicare Advantage Plans and How to Avoid Them

Disadvantage What It Means How to Avoid It
Provider networks HMOs and many PPOs work best when you use in-network doctors and hospitals. Check your doctors before you enroll, or choose a PPO that covers out-of-network care.
Prior authorization Some services need plan approval first, usually higher-cost care. About 92% of requests are approved. If one is denied, appeal; most appeals succeed.
Copays when you use care A $0 premium plan still has copays, coinsurance and deductibles. Compare total yearly cost: premium plus expected copays plus drug costs.
Out-of-pocket maximum The median in-network limit is $6,500 for 2027. Pick a plan with a lower limit if you expect heavy care; many plans come in under $5,000.
Referrals Most HMOs require a referral to see a specialist. Choose a PPO, or an HMO plan that does not require referrals.
Travel coverage Routine care is usually local, though emergency care is covered anywhere in the U.S. Choose a PPO with national out-of-network coverage if you travel often.
Benefits can change each year Plans can change premiums, copays, networks and benefits every January. Read your Annual Notice of Change each fall and switch during Annual Enrollment if needed.

Sources: CMS 2027 Medicare Advantage and Part D landscape data; Media Logic analysis of CMS CY2027 landscape files; KFF analysis of 2024 Medicare Advantage prior authorization data.

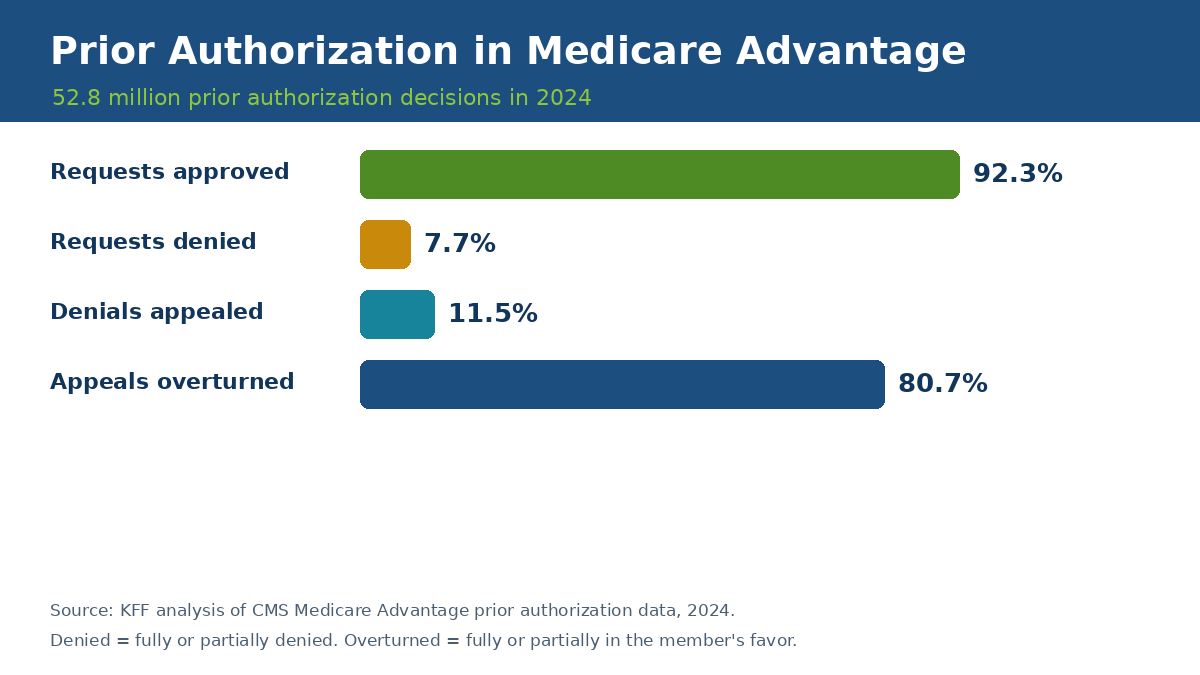
Medicare Advantage prior authorization 2024: 92.3% of requests approved, 7.7% denied, 11.5% of denials appealed, 80.7% of appeals overturned

Prior Authorization: What the Numbers Really Show

Prior authorization is the disadvantage people worry about most, but the data shows that most requests go through. According to KFF’s analysis of CMS data, Medicare Advantage insurers made about 52.8 million prior authorization decisions in 2024:

✔

92.3% were approved. Just 7.7% were fully or partially denied.

✔

Only 11.5% of denials were appealed.

✔

80.7% of appeals were overturned in the member’s favor, fully or partially.

Tip: if a service is denied, ask your doctor to help you appeal. Most appeals succeed, and many people never take that step.

Compare 2027 Medicare Advantage Plans in Your Area

Speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08

Out-of-Pocket Costs: Higher Limits, But Still a Safety Net

For 2027, the median in-network out-of-pocket maximum for individual Medicare Advantage drug plans is $6,500, up from $5,900 in 2026, and CMS allows up to $9,850. That limit sounds high, but most members never reach it, and it caps your costs in a bad year. Original Medicare on its own has no out-of-pocket limit.

✔

Shop the limit. About 31% of plans still have an in-network out-of-pocket maximum under $5,000 for 2027.

✔

Check hospital copays. Daily inpatient copays vary widely from plan to plan.

✔

Look at the drug deductible. It can be up to $700 for 2027, but some plans waive it.

Learn how drug coverage works inside these plans in our guide to Medicare Advantage Prescription Drug plans.

Networks and Travel: Pick the Right Plan Type

Network rules are the most common trade-off, and the plan type you choose decides most of it:

✔

HMO plans usually have the lowest costs and use a local network. See Medicare Advantage HMO plans.

✔

PPO plans let you see out-of-network providers, usually at a higher cost share. See Medicare Advantage PPO plans.

✔

Emergency and urgent care are covered anywhere in the U.S. with any Medicare Advantage plan, and some plans may include worldwide emergency coverage.

Who Medicare Advantage Works Best For

A good fit if you:

✔

Want low or $0 monthly premiums

✔

Like having medical, drug and extra benefits in one plan

✔

Are comfortable using a provider network

✔

Want a yearly cap on out-of-pocket costs

Look harder at other options if you:

!

Have specific doctors outside every local network

!

Spend months each year away from home

!

Do not want to deal with referrals or prior authorization

If you are in the second group, a PPO plan with a broad network can still be a good fit.

How to Choose a Plan That Avoids the Downsides

1

Check your doctors and hospitals in each plan’s network.

2

Run your prescriptions through each plan’s 2027 drug list.

3

Compare out-of-pocket maximums and hospital copays, not just premiums.

4

Choose the right plan type: HMO for lower costs, PPO for more flexibility.

5

Check the star rating. See the 2027 Medicare Advantage star ratings.

6

Enroll on time. Medicare Open Enrollment 2027 runs October 15 to December 7, 2026. You can also make one plan change from January 1 to March 31 during the Medicare Advantage Open Enrollment Period.

Compare 2027 Medicare Advantage Plans in Your Area

Speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08

Disadvantages of Medicare Advantage Plans — Frequently Asked Questions

➤ What are the main disadvantages of Medicare Advantage plans?

The main trade-offs are provider networks, prior authorization for some services, copays when you use care, and benefits that can change each year. Most can be managed by choosing the right plan type and checking your doctors and drugs before you enroll.

➤ Are Medicare Advantage plans bad?

No. Medicare Advantage plans cover 55% of eligible Medicare beneficiaries in 2026. They suit many people well, especially those who want low premiums, drug coverage and extra benefits in one plan, but they work best when you understand the network and cost-sharing rules.

➤ How often does Medicare Advantage deny prior authorization?

In 2024, Medicare Advantage insurers fully or partially denied 7.7% of about 52.8 million prior authorization requests, according to KFF. Of the denials that were appealed, 80.7% were overturned.

➤ Can I see any doctor with a Medicare Advantage plan?

It depends on the plan type. HMOs usually require in-network doctors except in emergencies. PPOs let you see out-of-network doctors, usually at a higher cost.

➤ Is there a limit on what I pay with Medicare Advantage?

Yes. Every Medicare Advantage plan has a yearly out-of-pocket maximum for covered Part A and Part B services. For 2027 the median in-network limit is $6,500, and the highest CMS allows is $9,850.

➤ Does Medicare Advantage cover me when I travel?

All Medicare Advantage plans cover emergency and urgent care anywhere in the U.S. For routine care while traveling, a PPO with out-of-network coverage is usually the better choice.

➤ Can I switch if I don’t like my Medicare Advantage plan?

Yes. You can change plans during Annual Enrollment from October 15 to December 7. If you are already in a Medicare Advantage plan, you can also make one change from January 1 to March 31.

➤ Are $0 premium Medicare Advantage plans worth it?

For many people, yes. About two in three Medicare Advantage drug plans have a $0 premium for 2027. Compare copays, the out-of-pocket maximum and drug costs to find the one with the lowest total cost for you.

New to Medicare?

If you are new to Medicare, then you can enroll in a 2027 Medicare Advantage plan up to three months prior to your Medicare Part B effective date.

Call one of our licensed insurance agents to see what the best time frame is for you to enroll, based on your current situation. You can contact them at 1-855-409-6195 (TTY 711), Mon–Fri 8am–9pm EST.

Have Questions?

Speak with a licensed insurance agent

1-855-454-9051

TTY users 711

Mon-Fri: 8am-9pm ET

Compare plans & benefits in your area

Or speak with a licensed insurance agent

1-855-454-9051TTY 711

Mon-Fri: 8am-9pm ET

Agent 08